

Instant Cash Advance: CashHoop
Biskup Apps
- 4.6
- 1.35K Reviews
- 1.00M
- Downloads
- Free
- Price
Screenshots
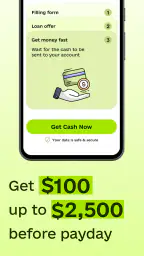
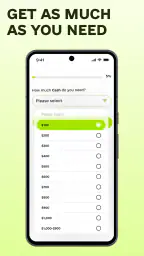
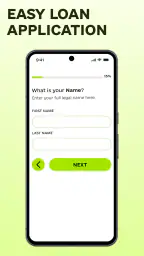
Instant Cash Advance: CashHoop Pros and Cons
Pros
- Simple application process with clear steps for requesting an advance.
- May help cover urgent expenses between regular paychecks.
- Account information and repayment details are easy to review.
- Useful reminders can help users keep track of upcoming payments.
- Convenient mobile access without visiting a bank or lender office.
Cons
- Eligibility and available advance amounts may vary by applicant.
- Fees or expedited-funding charges can increase the total repayment cost.
- Repayment is often due quickly, leaving little time to recover financially.
- Late or failed payments may lead to additional charges or account restrictions.
- Availability and terms may depend on your location and banking provider.
 Analysis by All-app
When an unexpected bill arrives, the hardest part is often not finding a financial app but understanding what will happen after you tap the first button. I approached Instant Cash Advance: CashHoop with that concern in mind. It is a free finance app from Biskup Apps, positioned around quick access to a cash advance and help with tax filing. The promise is straightforward, but the experience deserves a careful look because borrowing money is very different from checking a balance or tracking expenses.
My overall impression is that CashHoop is aimed at people who want to begin an urgent-money request from a phone rather than visit a branch or search through several separate services. It can also be relevant when tax work and an immediate bill appear at the same time. Still, I would not treat it as an automatic solution for every shortfall. The useful question is whether its process suits your situation, whether you understand the repayment responsibility, and whether you need speed more than a broader set of budgeting tools.
What to expect before using CashHoop
The app belongs squarely in the personal finance category, not in the same group as a traditional banking app, a full budgeting suite, or a long-term investing platform. Its central purpose is to help a user pursue a cash advance, while its store presentation also connects the app with filing taxes and handling unexpected bills. That focus makes the first session feel more task-oriented than exploratory.
I would install it with one specific goal already in mind. For example, you might be trying to deal with a utility bill that cannot wait, or you may be organizing tax-related work and want to see whether an advance is available through the app. Entering with a clear purpose helps prevent a common mistake: treating a borrowing tool as if it were spare income. The money may solve a timing problem, but it still creates a financial obligation that needs a plan.
CashHoop is free to install and is marked suitable for everyone. That describes the app’s age classification, not the financial suitability of every transaction. A teenager, a first-time borrower, or someone already struggling with several repayments should still approach the service carefully and involve a trusted adult or financial adviser where appropriate. The friendly presentation of a finance app should never replace reading the terms attached to an advance.
The app has built a noticeable audience, with over a million installs and a 4.6 average from around 26 thousand ratings. Those figures suggest that many people are willing to try it, but popularity is not a guarantee that an individual request will be approved or that the terms will suit you. In finance, the right decision depends on your income, timing, repayment capacity, and the exact offer shown during your own application.
One detail I would keep in mind is that CashHoop is relatively focused. If your main need is a detailed monthly spending plan, automatic categorization across multiple accounts, or investment research, a dedicated budgeting or banking app will likely be a better fit. CashHoop makes more sense when the immediate problem is access to a possible advance or a related tax task.
More Reads From Our News Desk

Switching to the Xbox App: What Changes in Your Gaming Routine

Coloring & Learn Review: A Satisfying Canvas, Cluttered Menus

Microsoft 365 Copilot on Your Phone: Who Actually Needs It?

Mafia City: The Crime Saga That Outshines Its Rivals

Woodturning Transformed: How OS Updates Enhance Your Craft

How Tiles Hop EDM Rush Redefines Music Gaming
How the first setup should feel
After installing, I would begin by checking that the app is the current release available for your device. The listed current version is 1.0.15, and it supports Android 7.0 or later. That broad operating-system support is useful if you use an older phone, although I would still keep the device updated and use a secure screen lock before entering sensitive financial information.
The first setup should be approached as an application process rather than a casual sign-up. Read each screen before continuing, especially wherever the app asks for personal, employment, income, tax, or account information. I would not rush through fields simply because the app is designed to move quickly. A wrong digit or incomplete answer can create delays later, and correcting details after submission is usually more frustrating than checking them at the start.
A practical way to prepare is to gather the information you are likely to need before opening the request. Keep your identification details, relevant income information, tax documents, and account details close by if the app asks for them. I am deliberately describing this as preparation rather than promising a fixed checklist, because the exact path can depend on the service flow and the request you choose. The important point is to avoid guessing when a financial form asks for precise information.
During setup, separate three decisions that are easy to blur together. First, decide whether you want to explore a cash advance. Second, decide whether you are using the tax-related side of the app. Third, decide whether the bill you are trying to cover is genuinely urgent. Keeping those questions separate makes it easier to stop if the offer does not match your needs instead of continuing simply because you have already entered information.
I also recommend reading the repayment details before celebrating a successful application. Look for the total amount you would need to repay, the timing, and any applicable charges or conditions displayed in the app. The word “instant” describes the intended speed of the experience, not a promise that every user receives money immediately. Approval, eligibility, delivery, and repayment can all depend on circumstances outside the simple act of installing the app.
Reaching the first meaningful result
For a first-time user, the most useful milestone is not merely opening CashHoop. It is completing a request far enough to understand whether the available option can realistically help with the problem you came to solve. I would start with the smallest amount that genuinely covers the immediate gap, rather than requesting more because the option appears available. Borrowing only what you need reduces the chance that a short-term fix becomes a larger repayment burden.
Suppose a necessary bill is due before your next paycheck. I would enter the request carefully, review every figure and condition, and compare the repayment timing with the date I expect money to arrive. If the repayment schedule would leave me short again, I would stop and look for another solution, such as asking the bill provider for an extension or using a less expensive source of funds. CashHoop can be useful for timing, but it cannot repair a budget that is permanently short.
A second realistic scenario involves taxes. Someone who has delayed filing may be tempted to focus only on getting money quickly. I think the better order is to organize the tax work first, understand what is owed or expected, and then evaluate whether an advance makes sense. Mixing an uncertain tax outcome with an urgent loan request can make the final financial picture harder to understand. The app’s combination of tax and cash-advance tasks is convenient, but it also means the user has to keep those obligations mentally separate.
When the app presents a result, slow down before accepting anything. Check whether the amount meets the actual need, whether the repayment date is workable, and whether the total cost is clear. Take a private note of the key details so you can compare them with alternatives. A screenshot may be useful for your own records if permitted by the app and your device, but I would avoid sharing financial screens through messaging or social networks.
The first successful action should leave you with clarity, not just speed. You should know what you requested, what was offered, what you will repay, and what happens next. If any of those points remain confusing, that is a reason to pause rather than a reason to tap through faster. In my view, this is the most important habit for using a cash-advance service responsibly.
Where first-time users may get confused
The biggest source of confusion is the difference between starting an application and receiving funds. A quick application flow can feel like approval, but those are separate stages. I would treat every early screen as information gathering until the app clearly shows the status and terms of the specific offer. This prevents the common assumption that installing the app guarantees access to money.
Another point worth watching is the difference between the amount you need and the amount you may be offered. If a bill is smaller than the available advance, taking the larger amount can create unnecessary repayment pressure. Conversely, if the offer is too small to solve the bill, accepting it may only postpone the problem. CashHoop is not automatically the best choice simply because it can provide some money; the amount has to fit the situation.
Tax language can also make a rushed session difficult. Tax filing involves deadlines, records, and accuracy, while a cash advance involves repayment. I would not use the advance part of the app as a substitute for understanding your tax position. If your return is complicated, your income varies, or you are unsure about a filing detail, professional tax help may be more appropriate than relying on a quick mobile workflow.
Privacy deserves practical attention as well. Before submitting information, I would check the app’s explanations of how information is used and make sure I am comfortable with the requested details. I would use a private network, avoid entering data on a shared phone, and sign out or secure the device afterward. These are sensible precautions for any financial service, but they matter especially when an app handles identity and income information.
There is also a difference between a free app and a free financial transaction. CashHoop costs nothing to download, but that does not mean an advance has no cost. The relevant information is the offer shown during the process, including any fees, timing, or repayment conditions. This is one of the most important trade-offs to understand: convenience at the beginning can be outweighed by an expensive or poorly timed repayment later.
Finally, do not assume that a high public rating answers your personal question. The app’s review count is substantial, and its average rating is strong, but users may have different income patterns, tax needs, urgency, and expectations. I would use those ratings as a reason to investigate the app, not as a substitute for checking whether the service is suitable for me.
When CashHoop is a good fit—and when it is not
I see CashHoop as a reasonable option for someone who needs a mobile-first way to explore a short-term cash advance and values having tax-related work nearby in the same app. It may suit a person who understands the difference between a temporary timing gap and a long-term affordability problem. It is also useful for someone who prefers completing an initial financial task from a phone instead of beginning with a branch visit.
I would be more cautious if your income is unpredictable, your next pay date is uncertain, or you already depend on several short-term advances. In those situations, another loan can make the cycle harder to escape. A credit union, employer-based assistance program, bill negotiation, or advice from a nonprofit financial counselor may be a better direction, depending on what is available to you. For a tax-only need, a specialist tax service may also offer a clearer workflow.
Compared with a bank app, CashHoop is more narrowly focused on the immediate advance journey rather than everyday account management. Compared with a budgeting app, it is not the tool I would choose to understand spending patterns over several months. Compared with visiting a tax professional, it may feel faster and more convenient, but it cannot replace personalized advice when your filing is complicated. Those comparisons help define its role: CashHoop is a focused option for an urgent financial task, not a complete replacement for every financial service.
One useful trade-off is speed versus deliberation. A phone-based process can reduce friction when a payment deadline is close, but fewer physical steps can also make it easier to accept an offer without thinking. I would deliberately add my own pause: write down the repayment date, compare the total repayment with the amount received, and check whether the next month’s essentials remain covered. That small workflow turns a fast app into a more controlled decision.
The next step after the first request
Once you have completed a request or reviewed an offer, I would not immediately make CashHoop part of a routine borrowing habit. Instead, use the experience to identify why the shortfall happened. If it was a one-time timing issue, create a reminder for the repayment and then rebuild a small emergency buffer. If it happens repeatedly, the more valuable next step is a budget review or outside advice, not another advance.
For tax work, keep your documents organized independently of the app. Save copies of submitted information where appropriate, note important deadlines, and check that the final result matches your records. The app can be a convenient place to begin, but your financial records should not exist only inside one mobile service. This is especially important if you change phones or need to explain a transaction later.
Biskup Apps has released CashHoop as a free finance app with a broad age classification and support for older Android devices, which lowers the technical barrier to trying it. The more important barrier is financial judgment. I would recommend installing it only when you have a clear reason, enough time to read the terms, and a realistic repayment plan.
My final view is positive but measured. CashHoop can make an urgent cash-advance or tax-related task feel more accessible, and its focused design is likely to appeal to first-time users who want a direct starting point. Its real value depends less on how quickly you can begin and more on whether the repayment fits your life after the emergency has passed. If you need a complete money-management system, a specialist tax adviser, or a safer long-term solution to recurring financial pressure, I would choose another option. If your need is temporary and clearly understood, this app is worth exploring carefully.
Frequently Asked Questions
What is Instant Cash Advance: CashHoop, and how does it work?
Instant Cash Advance: CashHoop is a financial app designed to connect eligible users with short-term cash advance or loan offers. After creating an account, you may be asked to provide personal, employment, income, and banking information so the service can assess your profile. CashHoop may then present available offers from third-party lenders or providers. Approval, funding speed, loan amounts, and repayment terms are not guaranteed and can vary by user and location.
Can I receive money instantly after applying through CashHoop?
The app may advertise fast decisions or quick access to funds, but “instant” funding should not be understood as guaranteed. The time required depends on eligibility checks, verification, the lender’s approval process, your bank, weekends or holidays, and whether additional documents are requested. Some providers may charge extra fees for expedited transfers. Always review the final offer carefully before accepting it, including the expected delivery date and total repayment amount.
What fees, interest rates, and repayment terms should I expect?
Costs can differ considerably because CashHoop may connect applicants with different financial providers rather than issuing every advance directly. Before accepting an offer, check the annual percentage rate, finance charges, origination or service fees, late-payment penalties, optional express-transfer fees, repayment schedule, and total amount due. A short repayment period can make even a modest advance expensive, so compare the complete cost with other available alternatives.
What personal information does CashHoop require, and is it safe to use?
CashHoop may request sensitive details such as your name, contact information, date of birth, income, employment information, bank details, and identity-verification documents. Before submitting anything, read the app’s privacy policy and understand which information is collected, why it is shared, and how long it may be retained. Download only from an official store, use a secure connection, and avoid giving account passwords or verification codes to anyone claiming to represent the service.
What should I do if I cannot repay a CashHoop advance on time?
Contact the relevant lender or provider as soon as you realize repayment may be difficult. Ask whether an extension, revised payment arrangement, or hardship option is available, and request all terms in writing. Do not ignore repayment notices, because late payments may lead to additional charges, collection activity, or possible credit consequences depending on the provider and local laws. Never take another expensive advance solely to cover an existing one without understanding the risks.


